
Dear Financial Samurai,
With the 10-year Treasury yield surging to 5.28%, the stock market is on edge. We got a slight reprieve Friday morning when we found out the U.S. added only 29,000 jobs in September, below the 84,000 consensus expectation. Yields dipped initially, but then zoomed higher to close the day.
Friday’s weak jobs data and the stock market rebound remind us that capital is a more efficient way to earn than labor. Not only is it harder to find work, it’s also harder to make more money at a job. But from an investor’s point of view, the less companies have to pay employees to keep them from quitting, and the fewer employees a company needs for the same productivity, the greater the profits and returns for shareholders.
In other words, you have to think like a capitalist, not a laborer. There are only so many hours in a day you can trade for money. Your capital, on the other hand, works 24/7 without asking for a raise, a promotion, or a ping pong table.
With the 10-year above 5.25%, we’re primed for a correction. Please make sure your liquidity situation is solid in case it happens.
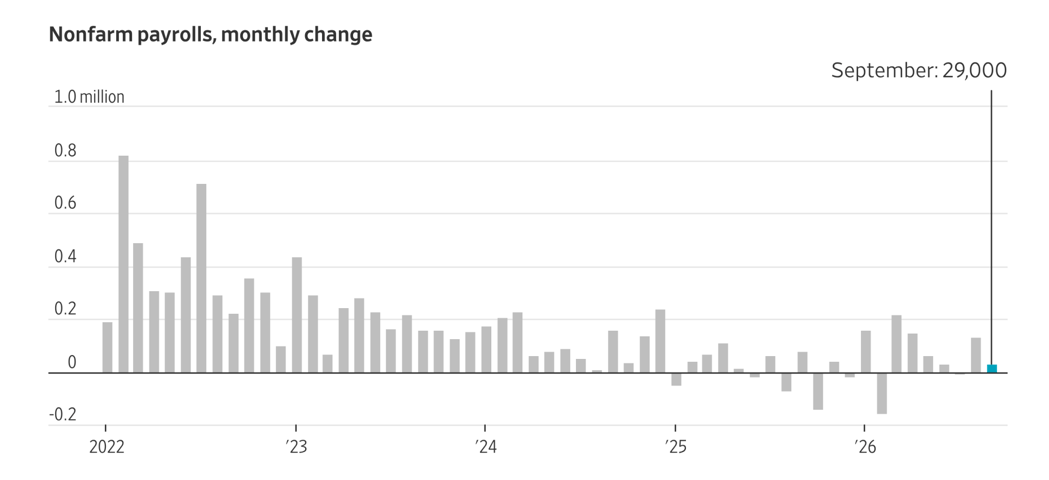
Ran Out Of Money
Speaking of a solid liquidity situation, I’m not in one. I’m temporarily screwed because a VC fund I committed a large amount of capital to has called far more capital than I expected in its first year. It’s the fastest I’ve ever seen a VC fund call capital in my ~20 years of investing in venture.
On the one hand, it’s good to see the firm winning promising deals. On the other hand, there is now huge vintage concentration risk in 2026. If 2026 turns out to be like 2021, forward returns will be terrible.
But perhaps more interesting for all of you is that the speed of these capital calls shows how quickly private AI companies are growing and how much appetite there is for them.
Instinct, the viral AI text messaging app, closed a $1 billion round at a $10 billion valuation last week. That’s after raising $250 million at a $2.5 billion valuation at the end of August. A 4X markup in about a month.
So as we patiently wait for Anthropic to go public in November, keep this private market mania in mind. If Anthropic can line up partners like Nvidia and Amazon to anchor $10 billion each at the IPO, that signal will likely ignite retail mania as well.
See: Broke Again At 49 And This Time There’s No House To Blame
Debt Is Not The Way In FIRE
Progress is happiness, and taking on debt to pay for things is not the FIRE way. Funny enough, debt is exactly how plenty of ultra-wealthy people fund their lifestyles. Instead of selling assets and paying capital gains taxes, they pledge their assets, borrow against them, and never sell.
Buy. Borrow. Die.
What I’ve realized is that once you’ve tasted freedom from work for a year or longer, you never want to go back if you are truly FIRE. Plenty of people take sabbaticals, go to grad school, or get laid off for a year and then itch to go back to work.
But if you truly have enough passive income to cover your basic living expenses, taking on debt feels completely backwards. Excessive debt is what ruins even the wealthiest men and women. Taking on debt increases your chances of having to go back to listening to another adult for 40-60 hours a week.
So if you want to go into debt to invest or YOLO (not recommended), do so before you retire. Because after you FIRE, you just won’t have the appetite.
Read: FIRE Makes Taking On New Debt A Non-Starter
Buying Your House Before The Liquidity Boom
The herd mentality is strong in all of us. Once Instinct launched its AI assistant via text, Meta launched its version in Muse. A week later, OpenAI launched its version in Dots. Google and Apple will likely follow shortly.
What are the chances all these companies independently planned to launch the same product within the same 30 days? Probably less than 3%. What really happens is one senior person sees what a competitor is doing and redirects all resources to ship a copycat ASAP. Nobody wants to miss out.
When it comes to housing, the herd behavior is even more intense. This fall could be the last “reasonable” time to buy a decent single-family house at a “reasonable” price for those with impending IPOs.
Bidding War Bonanza
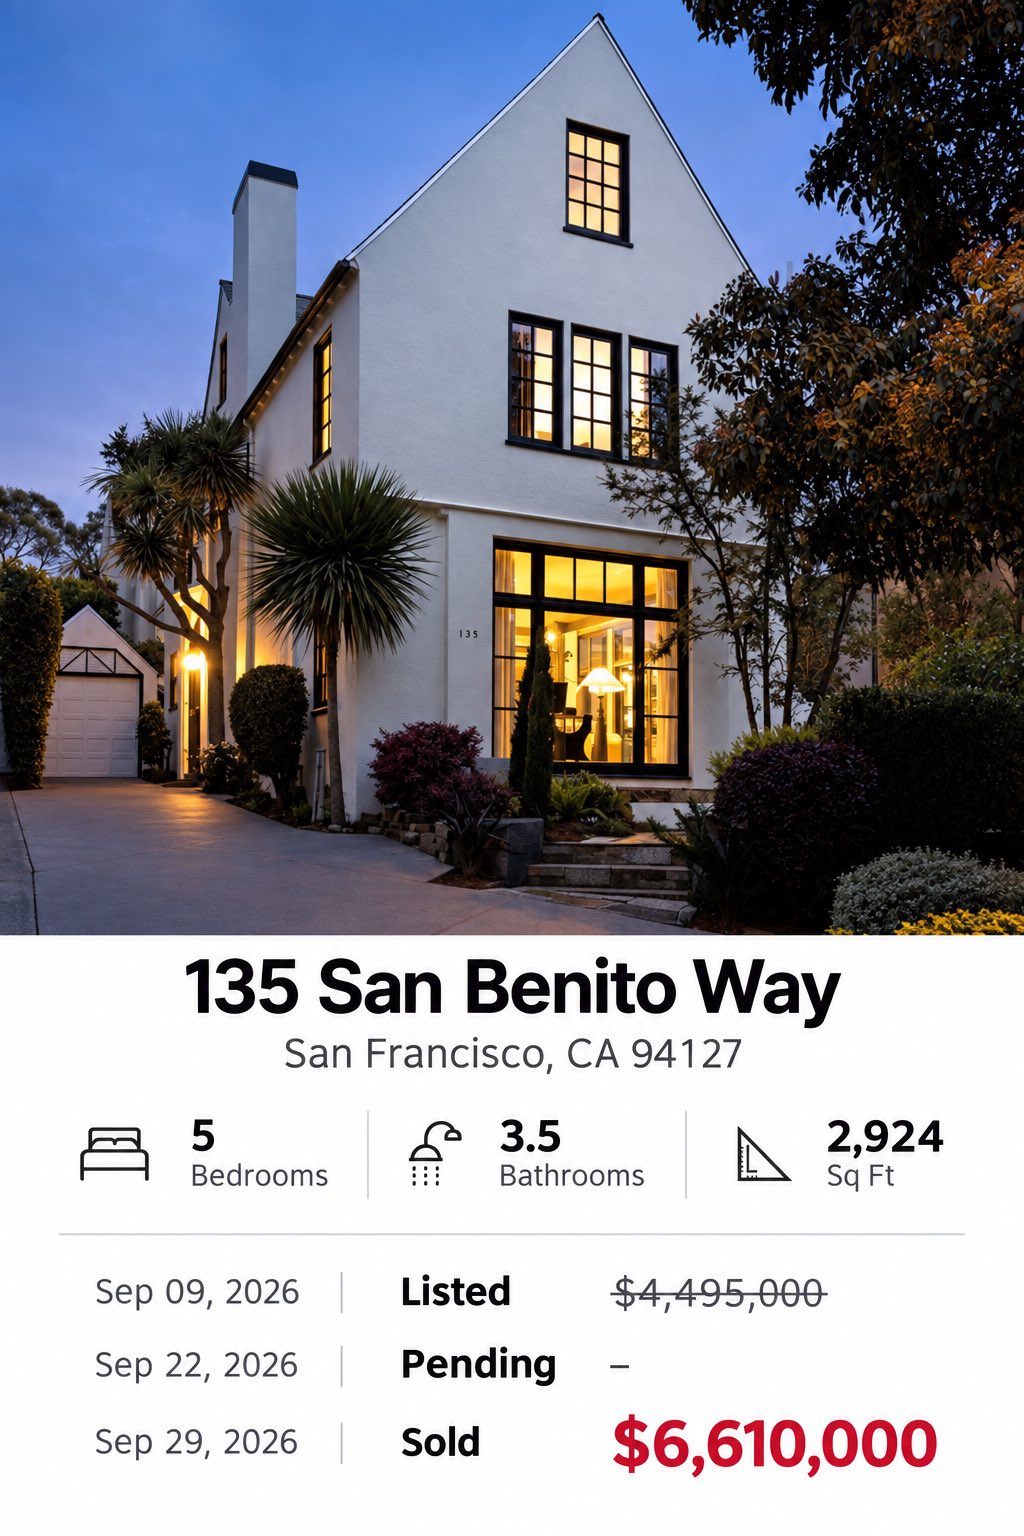
To give you an idea of how hot the SF market is for single-family homes, here’s a handsome 5-bedroom, 3.5-bathroom house with 2,924 square feet. I toured it. It’s a wonderful house in a great neighborhood I drive through five times a week to drop my kids off at school.
The main knock is that the driveway is practically shared with the house on the left. If your neighbor’s car is parked there, you can’t open your driver’s side door. The garage also can’t fit anything larger than a Mini. See what I’m talking about below.
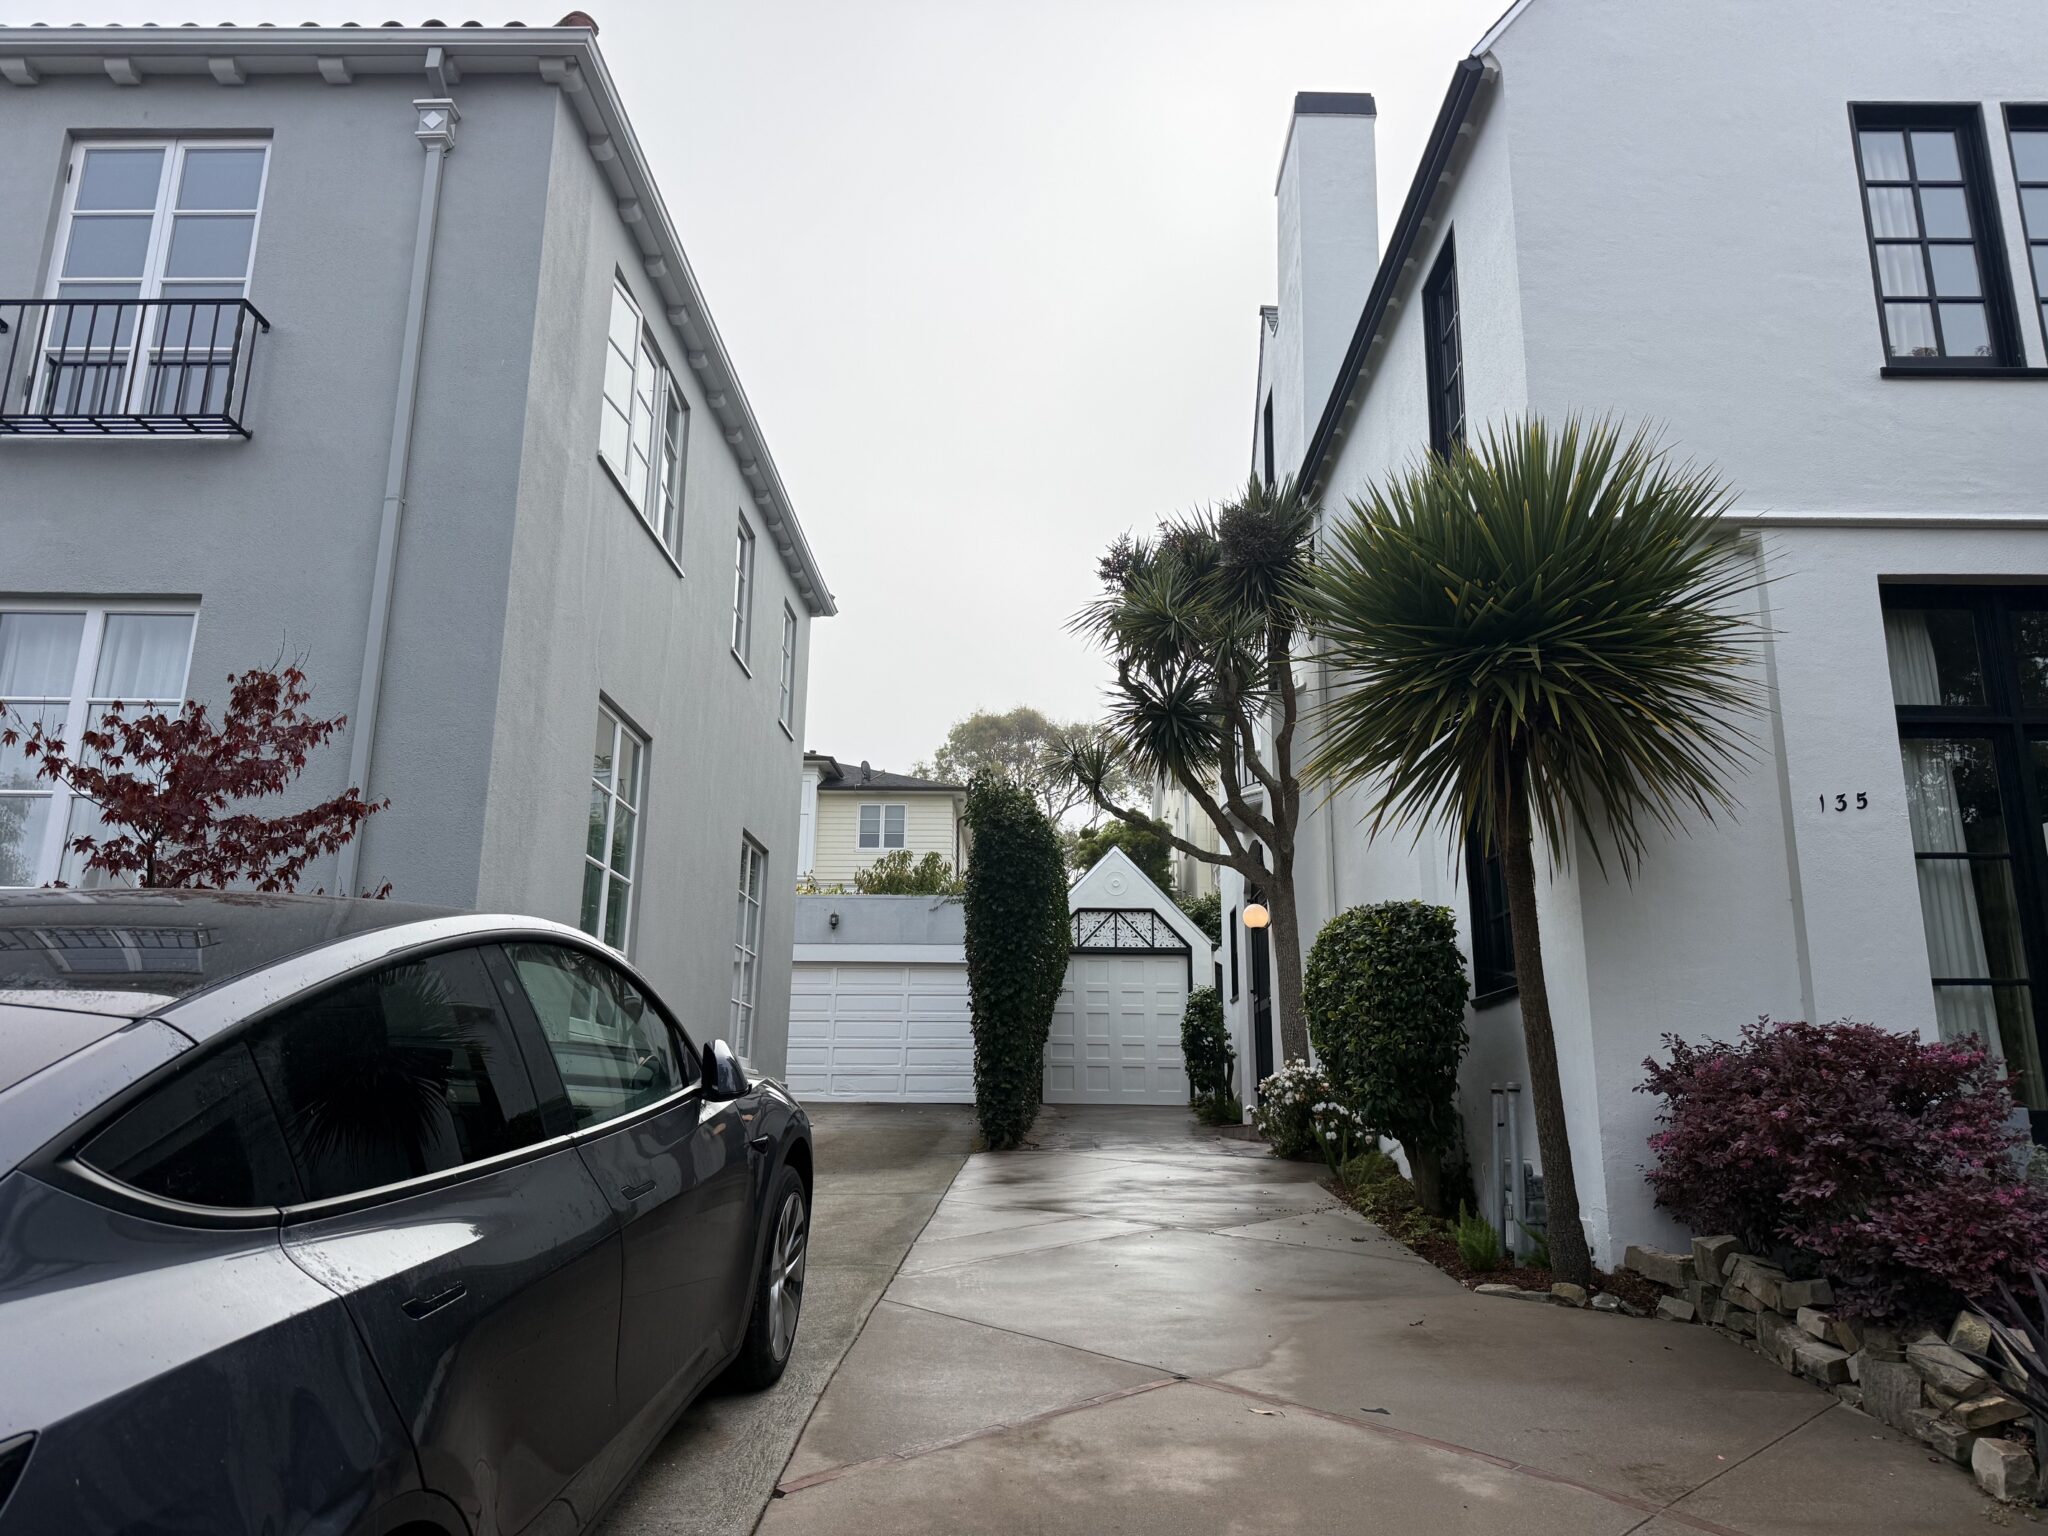
At only 2,924 square feet, the $4,495,000 asking price was already aggressive at $1,537/sqft, with no enclosed front yard and no view. I figured it would sell for $5.2 million at most. Instead, it closed for $6,610,000 in seven days. All cash.
So even I, a real estate nerd who watches the market closely and goes to multiple open houses a weekend, severely underestimated demand. The west side of San Francisco is booming.
Everybody Is Climbing The Same Property Ladder
As you climb the property ladder, know that it won’t be easy because so many others are climbing too. Instead of just competing with Bob or Nancy for the same promotion at work, you’re competing against people from all walks of life. If you find the perfect property, you can bet your buns of steel that plenty of others think it’s perfect too.
If you win the bidding war, congrats! Just know there’s one downside to living in a nice neighborhood nobody talks about, especially not the listing agent.
Check out: The Downside Of Living In A Nice Neighborhood
Patient Capital Wins In A High Rate Environment
While folks are fighting over $6 million houses in San Francisco, Fundrise is doing the opposite. With the 10-year above 5%, sellers who need to refinance or raise liquidity are under pressure. That’s when patient buyers with capital can find deals at higher cap rates and better value.
I like owning real estate this way because it’s passive. No bidding wars against all-cash buyers, no shared driveways, no tenants calling about a broken garbage disposal. It also lets me diversify beyond expensive coastal cities into the Sunbelt, where valuations are lower and yields are higher.
You can invest in Fundrise with as little as $10. Check out Fundrise here.
Fundrise is a long-time sponsor of Financial Samurai, and I’m an investor in Fundrise funds.
Forwarded This Newsletter?
If someone forwarded you this newsletter, join 60,000+ readers and sign up for free here. Please share this newsletter to anybody you think needs financial guidance and wants to break free sooner.
To get new posts in your inbox as soon as they’re published, ad-free for the first few hours, sign up here.
Money is too important to be left up to pontification. I’ve been writing from firsthand experience since 2009, and I’ll keep sharing what I’m seeing and doing with my own money.
To your financial freedom,
Sam