
Dear Financial Samurai readers,
I spent about two weeks with Mezzi, the AI investment advisor, putting together my new comprehensive Mezzi review. The deeper I got, the more impressed I was by how much it can do to help you build wealth.
I first used Mezzi for its Diversification X-Ray feature. It found about $300,000 more Google exposure than I thought I had. So I sold about $200,000 worth in my tax-advantaged accounts and put roughly 60% of the proceeds into the S&P 500. Good timing, because Google then fell about 15%.
Now I use Mezzi to flag where I’m taking excess risk and where I’m outperforming or underperforming. My new favorite feature tells me how long until each position flips from short-term to long-term capital gains if I sell.
The best way I can describe it: Mezzi is to traditional wealth management what the iPhone was to the BlackBerry. For DIY investors, it’s an incredible companion.
I’m proud to be an investor in Mezzi, and I encourage you to give it a try. Sign up for free and use code FS15 to save 15% on the Concierge or Advisory membership.
Tax-Efficient Selling
As I wrote a couple weeks ago, I’ve run out of excess cash because one VC fund has made greater than expected capital calls so far. If there’s another capital call in the next two months, I’ll have to start selling assets.
So I asked Mezzi a simple question. Assume I have $0 cash. What should I sell in my taxable FIRE account to raise $25,000 in an emergency, ideally with no capital gains, while also improving my risk exposure? Here was its answer.
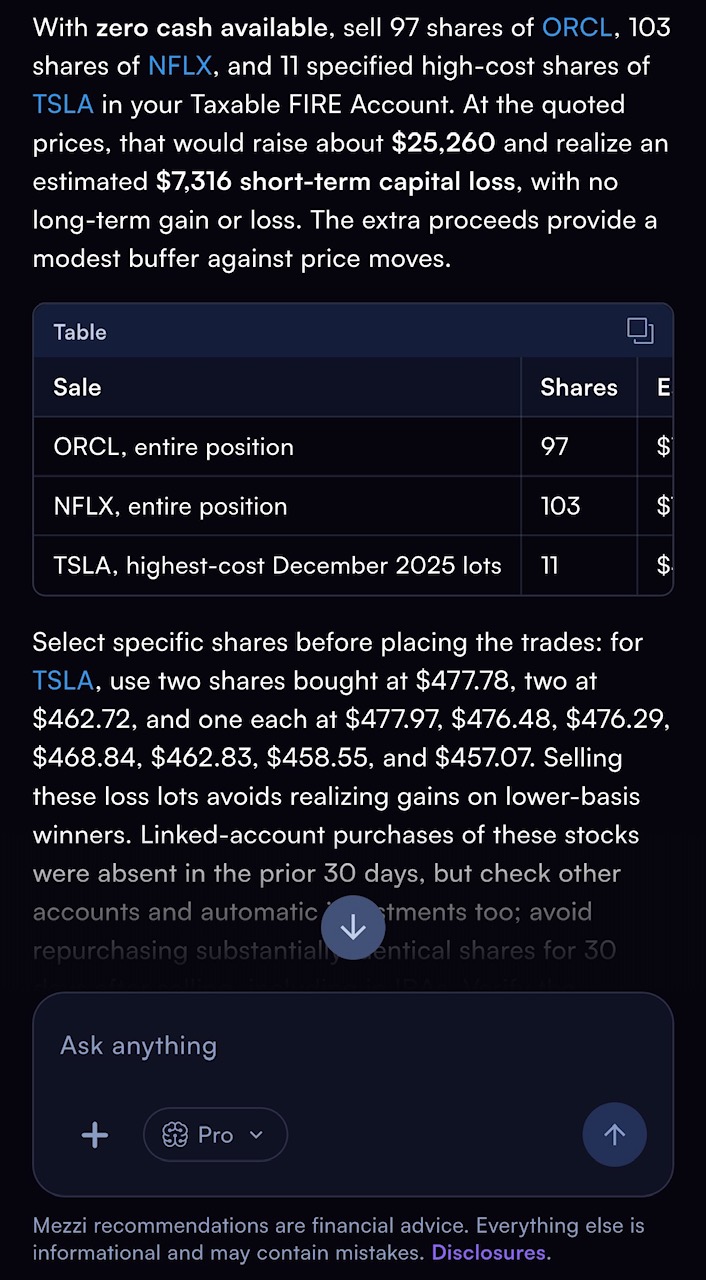
It reminded me I bought a few Tesla shares near the all-time high. Ouch. What was I thinking.
Then I asked whether I’d be better off engineering a net $0 capital gain instead of taking a $7,316 short-term capital loss. Mezzi pointed out I had short-term gains to offset, plus a lot more long-term gains sitting there.
I could not have easily figured out the most tax-efficient way to raise cash on my own. Mezzi knows all your historical trades, gains, and losses, so it can build a game plan in seconds. Whether I follow it when the time comes is up to me.
When Your Financial Back Is Against The Wall
This latest cash crunch has taught me something. When you’re in a tough financial spot, you find a way forward. Check out my new post: Manifesting Money When You Have None. I’m no longer convinced the fear of financial ruin is warranted.
One of our biggest regrets as we age is not taking more risks. Not just with investments, but with our careers, relationships, and creativity. Whether it’s fear of uncertainty, ridicule, or poverty, we tend to follow the herd and stay on the steady path.
If I could rewind 25 years, I’d tell myself to take that job at a competitor in NYC. Or relocate to Asia with my firm. Or stretch to buy a nicer SF property in 2003. Or deploy more capital during the Global Financial Crisis.
“You will regret the things you don’t do more than the things you try.” That’s what Conrad, a 56-year-old mailman, told me one day while we were chatting about life. The next year I left my job for good. Despite the bumps, I’ve never regretted it.
Risk For Your Children
I’ve also realized there’s risk in working an occupation that could shape your children’s career paths. Kids observe everything their parents do and feel, even if they don’t say so.
So whether you’re an unemployed FIRE parent or someone in a job you love that doesn’t pay well, be careful sharing too much about your career. Unless you’re fine with them following the same financial path.
My kids mostly think I’m a writer. They’ve seen my two books at the library and bookstore. Now they’re writing books of their own, which is awesome. It’s also concerning, because being an author is one of the lowest-paying professions out there.
The median book advance is under $20,000, often paid out over two or three years. If you’re a parent in a poorly paid profession, this new post offers a solution and something to chew on: Children Doomed To Follow In Their Parents’ Footsteps.
Traveling With The Family
By the time you read this, my family and I will be on our fourth day in Las Vegas. I wrote this newsletter before we left. It was a relatively last-minute trip since the kids had no school Thursday and Friday. They’ve never been.
The only problem is it comes at a tight financial time, so the wagyu steak dinners with caviar are out. McDonald’s filet o’ fish, my son’s favorite, it is.
But as a financial writer, that also makes it the perfect time to explore how to give your family the best life possible with limited resources. And since it’s Vegas, there’s always the temptation to gamble your way out of a financial problem. I don’t recommend it. But the posts should be fun to write.
Thanks again to Mezzi for supporting Financial Samurai and creating an incredible product. If you have questions after signing up, email Manish@mezzi.com and tell him I sent you. Manish is the co-founder, and we had lunch here in San Francisco this summer.
Sign up for free and use code FS15 to save 15% on the Concierge or Advisory membership.
To your financial freedom,
Sam
Forwarded This Newsletter?
If someone forwarded you this newsletter, join 60,000+ readers and sign up for free here. Please share this newsletter to anybody you think needs financial guidance and wants to break free sooner.
To get new posts in your inbox as soon as they’re published, ad-free for the first few hours, sign up here. I’ve been writing from firsthand experience since 2009.