
This week’s newsletter is sponsored by Fundrise, my preferred platform for private real estate and private equity investments. With just a $10 minimum, it’s an accessible way for anyone to gain exposure to high-quality residential and commercial real estate, along with private growth companies—especially in the AI sector. I’ve personally invested over $500,000 across various Fundrise offerings so far.
Dear Financial Samurai,
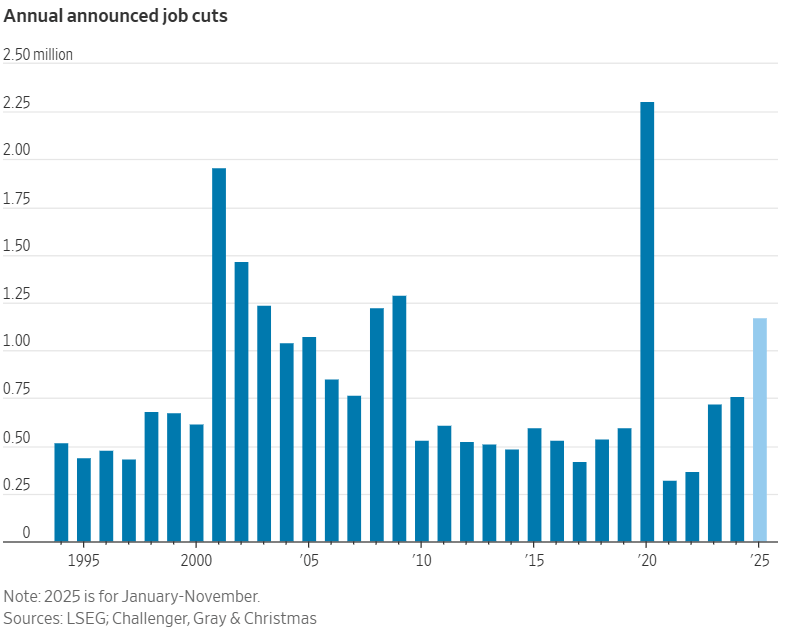
The biggest economic news this week is the clear softening of the U.S. labor market. In November, private companies cut 32,000 workers according to ADP’s latest report. The slowdown is real, and it’s picking up speed.
The silver lining? There’s now roughly an 89% chance of another 25-basis-point Fed rate cut on Wednesday, December 10. More easing, more liquidity, more oxygen for risk assets. The not-so-silver lining? Treasury yields keep rising anyway, with the 10-year back up to 4.14%. Mixed signals everywhere.
Still, so long as you keep your job, the backdrop is turning more supportive. Rate cuts are coming. T-bill buying is pushing cash into the system. And next May, we’re likely getting a significantly more dovish Fed chairman—Kevin Hassett—once Powell steps down. Monetary policy winds are shifting.
Having Skin In the Game Makes A Difference
Another striking headline this week: the Dell family has pledged $6.25 billion to help fund “Trump Accounts,” giving 25 million children born between 2025 and 2028 an extra $250 on top of the initial $1,000 seeded by the government. If several more billionaires join the effort, we could be looking at $2,000 starter accounts.
Ownership changes behavior. I still remember the first moment “ownership culture” clicked for me at 23. I was walking back from the bathroom on the 49th floor of 1 New York Plaza – Goldman’s international trading floor – when I saw a crumpled piece of paper in the hallway. I picked it up without thinking, partly out of pride, partly because I had been granted around $10,000 in stock. When you’re an owner, you instinctively take care of your environment.
It’s the same with homes. If you own your place, you’re more likely to pull the weeds and keep the lawn tidy. If you don’t, maybe you let the plants overgrow and host loud gatherings until 1:30 a.m. Ownership drives responsibility.
So if the government is explicitly aligning itself with the stock market, then it makes sense for the rest of us to stay invested as well. It’s no different from housing—when policymakers want more ownership, incentives inevitably follow. And based on what I’m hearing, expect fresh housing incentives to surface in the new year too.
America Continues To Love Cars
I always get a little extra jolt of excitement whenever I publish a car-related post because the enthusiasm is unmatched. My latest one—Time To Buy A New Car: Mine Is 10 Years Old And Causing Too Many Problems—was no exception. I loved hearing about all the different cars you drive, the issues you’ve run into, and the clever solutions you’ve found. I even picked up a few new insights about Tesla’s latest features and the Lexus GX 550.
That said, buying a car today is a total PITA. I used to love wandering through dealerships, test driving whatever caught my eye, and soaking in that glorious new-car smell. But now? The idea of small talk and haggling makes me want to take a nap. I’d rather just keep driving my old car into the ground. Unfortunately, constantly paying for repairs, and losing hours at the mechanic, isn’t exactly ideal either.
This whole process reminded me why my favorite personal finance framework is the House-to-Car Ratio. It’s shockingly effective at keeping people on track to build real wealth. And after talking to dozens of people during my car-buying exploration, it’s clear that far too many House-to-Car ratios are wildly out of whack.
Maybe Housing Is Cheaper Than Everyone Thinks
Ever since I started Financial Samurai in 2009, I’ve been hearing about a housing affordability crisis. And yes, housing prices did fall during the 2008–2009 financial crisis. But stocks also tanked, layoffs surged, and job security evaporated. Even if you spotted a cheap house, buying it required a leap of faith that many simply couldn’t stomach.
Fast forward to today: we’re in the middle of a raging bull market. The majority of Americans own stocks, which means the majority have benefited. Meanwhile, home price appreciation has cooled dramatically – or reversed – in several pandemic boomtowns.
So here’s my contrarian take: housing affordability might actually be at an all-time high (new post), despite what politicians, economists, journalists, and real estate pundits claim.
Want to test the idea?
Just compare your portfolio value today versus in 2020. If your stock gains exceed the 20% down payment you’d need for a house now versus back then, today’s housing market is more affordable for you personally.
Only two readers said I was “out of touch with reality,” implying that their reality is more legitimate than mine. But I continue to see the same pattern: people tell me “everyone else is struggling,” while they themselves are doing just fine.
Sometimes we need a humble reminder: we are not the exception, we are everybody else.
The Better House Option
Given how much your favorite tech stocks or S&P 500 ETFs have likely ballooned since 2000, you may finally be thinking about putting that “funny money” wealth to work by buying a home. With that in mind, I put together a post comparing the two features single-family homebuyers covet most: an incredible view or a generous, usable lot.
Sure, owning a home that sits on a massive lot and offers breathtaking water views would be ideal. But properties like that are rare—and usually priced in the stratosphere. For most of us, the smarter move is choosing the option that best aligns with our lifestyle, priorities, and stage of life.
Just be warned: once you buy a home with a great view, it’s hard to ever go back to staring at the back of another building. And once you experience the freedom of having real space and land, returning to cramped quarters will feel like a major downgrade, unless you truly have no choice.
Read: A Big Lot Or Amazing Views: Deciding Which Home Offers More Value
Another Exciting Week Ahead
Let’s enjoy Fed week. If we get the rate cut, we might even see a sell-on-the-news reaction in stocks, which would be a welcome buying opportunity heading into what’s shaping up to be another strong year in 2026.
And with Treasury yields still elevated, I’ll be rolling some of my expiring T-bills and notes into fresh ones to lock in the higher rates while they last.
To Your Financial Freedom,
Sam
Thanks again to this week’s newsletter is sponsored by Fundrise, my preferred platform for private real estate and private equity investments. With just a $10 minimum, it’s an accessible way for anyone to gain exposure to high-quality residential and commercial real estate, along with private growth companies.
Join 60,000+ others and sign up for my free weekly newsletter here. My goal is to help you achieve financial freedom sooner, rather than later. You can receive my posts in your inbox immediately after they are first published without ads by signing up here.