
If you wait too long to start spending your money, you will have wasted many years of unnecessary work, stress, and worry. You'll have traded your best decades for a number on a screen that eventually gets passed to someone else.
After another summer living with my parents, I'm even more convinced about 45, my recommended start of decumulation. Not because the math changed, but because I watched the alternative up close for two summers in a row.
Here's the realization: you won't be able to spend all your money when you're old. Not “you shouldn't.” You won't be able to. The ability and the desire itself disappears.
And when I say old, I'll peg that age at 65+, the traditional retirement age when corporations no longer deem you productive enough to keep around.
The Inability To Spend Money When You're Old
If you want to get a glimpse of how you'll be when you're old, simply spend more time with your parents when they're old. After all, children are highly influenced to follow in their parent's footsteps in many stages of life. Spending time with your elderly parents will give you a clue as to how you’ll be when you’re their age.
My parents used to love going on cruises to various parts of the world. It was one of the ways they enjoyed their wealth in retirement.
Then COVID hit and their cruising enthusiasm never came back. When I asked them why they don't go anymore, they said they can't be bothered. They also don't want to risk getting sick.
So I offered to pay. A nice cruise, balcony suite, any duration, any location. My treat.
They declined. This makes me sad as I fondly reminder seeing the joy on both my parent's faces every time they went to the buffet.
The single largest barrier to spending money, the money itself, was removed entirely. And they still said no.
Upon second thought, maybe money isn’t the biggest hurdle since they have pensions. It’s simply just their lack of interest and their desire to stay healthy.
No Excursions With The Family Either
One of my favorite childhood memories was going to Hanauma Bay with my father. We walked down and up the hill no problem. We even ran into Robin Williams. But when I decided to take my own kids for the first time this trip, I already knew he wouldn't want to come, so I didn't even ask.
Instead, he enjoys hours of free TV programming at home. My mom does too.
So I feel great knowing I bought them the largest new TV that would fit on their stand. For over a year, they had been watching a blurry TV, and just chalked the image up to poor eyesight.
But even the finest 60″ TV from a retailer now costs under $1,000. So cheap for years of entertainment.
Inexpensive Board Games
Not one to give up easily on finding fun things my father can do with us, I first got him to play Monopoly Junior with my son and daughter. That worked until my boy lost interest after the first game. Then my daughter chucked a game piece on the ground after losing a second time. Monopoly Junior is almost entirely luck, so it stops being fun pretty fast.
The second evening, I switched to chess, a game my father used to play constantly. He was enthusiastic, and so were the kids. One of my fondest memories is playing him about 10 years ago after snow bowls for dessert. This time it was my dad versus both kids. They had a lot more fun, even though they still got crushed.
Each game cost about $20 at Target. They will be played dozens of times.
That's the entertainment budget of two people in their 70s and 80s with no debt and pensions. Board games and a TV antenna, not even cable. The rest of their spending is food, taxes from required minimum distributions, house maintenance, and property taxes.
The travel and the big-ticket experiences are simply gone.
Frugality Compounds, And Not Always In A Good Way
Here's the part that makes it worse. My parents have been frugal their entire lives.
They didn't become careful with money after they retired. They were careful at 30, at 40, at 50, and by the time they hit their 70s, thrift wasn't a strategy anymore. It was part of their DNA.
We spend so much time talking about how compounding works on the asset side. Nobody warns you that it also works on the behavior side. Forty years of telling yourself “no” builds a muscle that gets very hard to relax.
You can hand a lifelong saver a spreadsheet showing they can safely spend $50,000 more a year and they will still hesitate over a $12 shave ice. The number doesn't matter. The wiring does.
This is the cruel joke of the FIRE movement that nobody puts on a chart. The exact discipline that gets you to financial independence is the thing that prevents you from enjoying it.
I have friends worth eight figures who still won't upgrade their 11-year-old car with electrical gremlins. They aren't being smart. They're being trapped by a version of themselves from 1998 who genuinely couldn't afford it.
Could This Be My Destiny?
When you're younger, it's easy to say your life will look different from your parents' when you get to their age. Then you catch yourself doing the exact same things.
I remember when my dad was 49, because I was 17, finishing up my senior year of high school and getting into a fair amount of trouble. He worked a regular job and came home with my mom around 5:30 or 6pm.
So we're different in that respect. I stopped working a day job five years before we had our son.
But I forgot that my dad and I used to play golf together whenever I came home to Honolulu. That hasn't happened in about 10 years. He lost interest and physical mobility. There was no longer enough time or motivation to get out there.
Here's the thing. I don't find golf that fun anymore either after being infatuated with the sport in my 30s. I only go when someone invites me to a corporate outing or their club, which is only two or three times a year. I'd rather play pickleball and tennis, but my body is wearing down too with increasing injuries.
Since graduating from college in 1999, I've never gotten into the habit of watching more than two hours of TV a day. Most days I watch none, just short video clips online. After all, I cut cable, remember this year. A long time ago I decided producing content was more fun than consuming it. It was also more profitable.
But if I don't end up watching a lot of TV as my cheap entertainment, I'll probably just play pickleball, go to the beach, or go hiking instead. Surprise surprise, all of those are free.
So when I was facing a liquidity crunch and my wife wanted us to vacation in Las Vegas, I decided to YOLO. I wasn't going to let my silent stress keep us from a memorable experience.
How About Spending On Cars And Houses?
My parents drive a 28-year-old car. That means my dad has been driving the same vehicle since he was 54 and I was 21. At 49, I'm not that far behind. I've had my 2015 car, bought a year old, for 10 years now.
I could easily see myself keeping my next car until it disintegrates. The thrill of owning a fancy new car died for me around age 32. Now I want reliable, safe, and roomy enough for a family of four. Once both kids are out of the house, I'm not sure I'll need to buy anything nicer. I only drive 6,300 miles a year as it is.
Finally, my parents live in a paid-off home my grandparents built in the 1980s, after tearing down the previous house that was infested with termites. The house is too big for them, but it's great when we visit, especially now that I've finished remodeling the two-bedroom in-law unit.
Unless they want to move into a two or three-bedroom condo with amenities, they aren't spending money on property either.
We found our forever home in San Francisco after climbing the property ladder for 20 years. We won't be upgrading if we stay in the city. If we move to Honolulu, we might buy a cheaper house since prices are more affordable there.
Hmm. Almost every single line is me becoming my father, just on a 33-year delay.
Spending Money Aggressively Past 65 Provides Declining Joy
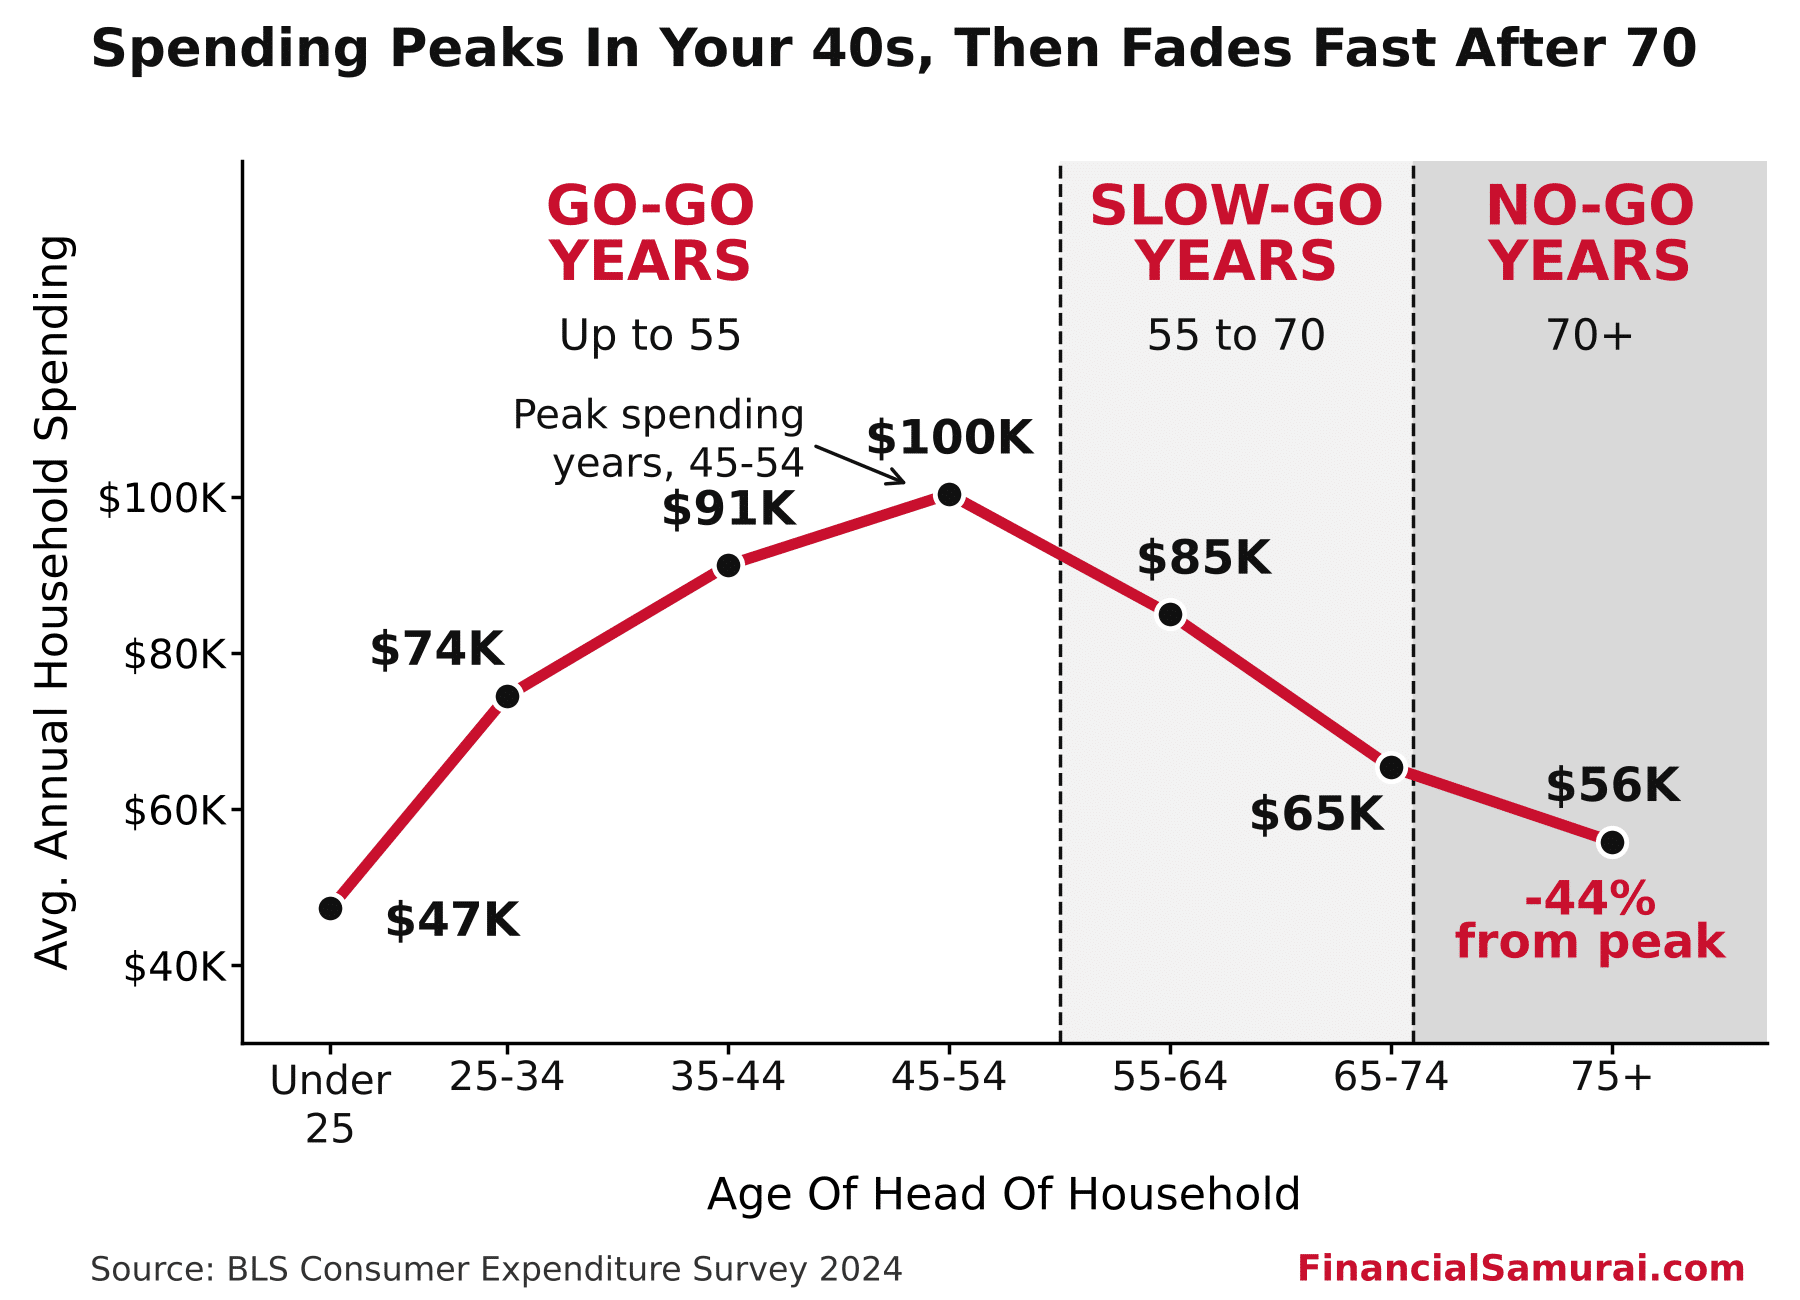
Ages 65 to 70 is not that old, assuming your health is intact. But I've clearly watched my parents slow down after 70. Maybe there are being extra cautious due to the high cost of eldercare. I need to ask.
Besides yummy food and fitness, there is genuinely nothing money can buy them that brings more joy. The only thing I came up with is hiring a reliable house cleaner once a month for $500. And even that would come out of their cash flow, not savings or investments.
Which means the only way my parents will ever decumulate their wealth is through a bear market. A decline that provides them nothing in return. That's it. That's the exit.
Their money will not be spent. It will simply be transferred, either to the market on a bad year or to me and my sister.
But, I don't want it. I have my own money. I built my own thing specifically so I would never have to think about theirs. Every dollar they don't spend is not a dollar I'm quietly rooting for. It's a massage they didn't get, a cruise they didn't take, a business class seat they suffered through coach to avoid.
I'd trade the entire remainder for two more good years of them enjoying themselves.
15-20-Year Window To Spend With Joy When Older
So when I look at my life at 49, and at their lives after retiring in their 60s, it becomes obvious that there's only about a 15-20-year window to spend money intentionally.
You don't want to spend heavily before 45, because there's too much life left and probably dependents to care for. But after 45, it's go time. That window closes faster than anyone expects, and it closes from the inside.
If you FIREd well before 65, ironically, you may need to spend even more aggressively. You accumulated enough capital to retire early in the first place, which means you benefited more from the bull market than the average worker who can't live off investments alone.
A 4% or even 5% safe withdrawal rate has simply been too conservative since 2012. Your net worth is far higher than when you first retired.
What I'm Actually Going To Do About It
After observing my parents in detail for two straight summers, I'm going to work harder at consumption spending.
I tried my best with the $40,000 earmarked for the Summer YOLO Fund and failed spectacularly, spending only 20% of it. But I still spent more than I would have without setting an intentional target, so the exercise wasn't a total waste.
I also used the remaining funds to invest in Mezzi, the AI investment advisor I think is incredibly helpful.
America generally thinks spending money on private school is a waste. I don't, so that expense is covered. My home is set for now, though I'm considering something nicer in Honolulu.
What's left is upgrading my car, eating absurdly expensive food I don't need, and donating more to charity.
I've also got to stop treating investing like a luxury expense. Investing has been one of my biggest hobbies for the past 30 years, and it's almost impossible to stop. It brings me so much joy!
Finally, I'd love to live long enough to see and help take care of my grandchildren. Hence, more money to physical and mental health.
The Funny Part Of Not Spending
Ironically, my parents seem happy. Or maybe the better word is content.
If you asked them whether they're missing out on anything, they'd look at you like you asked whether they're missing out on scuba diving. Not at all.
So who exactly is the unhappy one here?
Maybe I'm projecting. Maybe I'm looking at their life through the eyes of a 49-year-old with a functioning body and a to-do list, and mistaking a calmer life for a lesser one.
Or maybe contentment is just what a lifetime of frugality feels like from the inside, and there's no way to tell the difference between peace and adaptation from the outside.
I don't know.
For myself, the lesson is simpler. Front-load the spending after age 45. Do the trip while your knees work. Buy the thing while you still want things.
Because the money will absolutely still be there at 75. You're the part that won't be.
Reader Questions
Have you watched a parent become unable to spend their money, even when they clearly could afford to? At what age did the shift happen?
If you're a lifelong saver, what's the largest purely discretionary purchase you've made in the past year, and how long did you agonize over it?
Do you believe you'll spend more freely in retirement than your parents did, or is that the same thing every generation tells itself at 49?
Get Life Insurance To Shore Up Your Spending Confidence
One reason lifelong savers can’t spend is fear. What happens to my family if something happens to me? So we hoard, just in case.
Term life insurance is one of the cheapest ways to take that fear off the table. Once your family is protected, every dollar you spend on a trip, a nicer meal, or a better car stops feeling like a dollar stolen from your kids’ future.
Policygenius makes it easy to compare quotes from top-rated insurers in one place, so you can find the right coverage at the best price.
Protect your family first. Then go enjoy your money while you still can.
Use A Great Retirement Planning Tool
If you want to know how much you can actually spend down without running out, you need to see everything in one place first. I've been using Empower's free financial tools since 2012 to track my net worth, x-ray my portfolio for hidden fees, and run their Retirement Planner. The planner is what convinced me my safe withdrawal rate was too conservative in the first place.
Most people spend too little in retirement because they've never modeled what “too much” would actually look like. Run the numbers and find out where your real ceiling is. It's free to sign up and takes about 10 minutes to link accounts.
If you link over $100,000 in investable assets, you can schedule a free financial review with a professional. I've done so three times in the past 14 years, and each time has been helpful in highlighting potential blindspots to help me build more wealth. I'm not currently a client, but an affiliate.
Newsletter Signup
If a friend forwarded you this post, welcome. Join 60,000+ readers who get my free weekly newsletter at financialsamurai.com/news.
You can also get notified the moment new posts publish by signing up at financialsamurai.com/email. Posts go out ad-free for the first few hours to subscribers.
Everything I write comes from firsthand experience, because money is too important to be left up to pontification. I've been sharing it since 2009.

Thanks, Sam, for this thoughtful post. Your point that waiting too long to spend means trading your best decades for a number on a screen, and your suggestion to start decumulation around 45, really stuck with me. Would it be okay if we gave this post a shout-out on the Unstoppable Empire podcast? It would really help our listeners, and I’d send you the episode before it airs.
Absolutely! Share away. Thanks for reading.
Thank you so much, Sam! Your shout-out will most likely be in Tuesday’s Unstoppable Empire episode. We’ll send you the link as soon as it’s live. Thanks again for the great post.
Remember, you’re only one win away! Keep building your empire.
Dallas Cousins, Unstoppable Empire
Thank you again, Sam! Dallas gave you the shout-out on today’s Unstoppable Empire podcast episode, airing at 7 AM Eastern as our newest episode. Have a listen here: https://drive.google.com/file/d/13EVeBWzf1yooA55t21fGvCkBfc7NOTHi/view
Hi Sam, Dallas here from Unstoppable Empire. Thank you for your reminder not to postpone living while chasing financial goals. It meant a lot, so you got a shout-out on today’s episode, “How to Measure Business Progress.” Thank you for letting us feature your work!
Apple: https://podcasts.apple.com/us/podcast/unstoppable-empire-how-to-start-a-business-while/id6800521090?i=1000799599198
Spotify: https://open.spotify.com/episode/6P7QyOXdJYfBxXJPVMiC6L
Very cool! I’ll have a lesson during today’s Hot tub session. Thanks for the shout out.
That’s awesome, Sam, thank you! Enjoy the hot tub session. We’ll keep sharing your work with our listeners.
You made me laugh out loud with “the look of joy on your parents faces at the buffet”. I think you just described me. So much truth in your article. I’m frugal, my parents were frugal, my grandparents were frugal. It’s in the DNA. I barely use my pension income, let alone investment returns. So far, at the age of 71, still interested in travel. Usually do it independently, no tours or cruises. My excuse for frugality, is the desire to leave my daughter an inheritance, because the world kind of sucks. But that’s an excuse, I’m just plain cheap. Maybe, your parents could be convinced to go on a cruise or tour if every single detail is handled for them? Sometimes it’s the planning/logistics that’s exhausting.
I’m in this phase right now. I retired at 57 which is early but not as early as I would have liked. Still I feel grateful. I’m having to spend a bit more aggressively than I’m comfortable with but we did this year! This article is well aligned with my thinking and also “Die with Zero” which is one of my favorite financial books (and also my strategy/plan). I think it might be interesting for you to consider writing some articles about other related topics that overlap.
This is one of my favorite articles ever! I do have saved and saved and have more than enough… But to ask myself, what do you want? I’m recently Widowed in a weird weird spot. And mostly I don’t know what I want. But I do enjoy spending time with my kids and going on trips with them and I think I’ll do more of that. As well as mostly hobbies, but they are almost free…
You are right we’re just accumulating. I never thought of it. I have a hard time not living in scarcity. I love your post and I love when you make us think about our lives and our income. Thanks, Sam.
Hi Kelly – Thanks for commenting and glad this post resonated with you. I’m sorry for your loss. I’m glad you’re spending time with your kids and going on trips. So much precious time gets wasted on accumulating more money we don’t need.
All the best!
Preaching to the choir Sam. I just dropped about $3k on LA Phil/LA Opera/Hollywood Bowl/Ballet tickets for the next year and spend about $3k/year on French lessons with zero regrets and a fullness of life.
I just had to click on this article, as I’m living it. I’ve been on my own pretty much since age 16 and I’m 66 now. After a very early career in IT, I worked as a DOD contractor for a employee owned company for 35 years. I had a serious conversation with myself about 10 years ago after my divorce. I decided what I really wanted from life, was to not have to work. I was already living well below my means and investing the rest. Every raise went to the 401k and the Roth catchup until it was maxed for the year. I lived on the same paycheck amount for 10 years. I own 3 vehicles all with over 190k miles, the newest being ia 2013 Honda Pilot. Any extras I wanted I paid for from my side business selling antiques, collectibles and junk, so I’m addicted to picking / treasure hunting. My job was extremely stressful as mistakes could cost warfighter lives. The treasure hunting became diversion therapy for the stress. But eventually my stress induced high blood pressure pushed me to retire In August of 2023. The market dropped significantly right after and I had left a highly compensated (for the East Coast) position. I was able to work from home with great benefits. But I got to where even dialing in to a daily 9AM meeting was just too much. Since retiring, I have taken 4 specialty music cruises and been on several trips around the US. I’m planning another cruise in January and an Italy trip of 2 weeks alone. Then I will meet friends in Sicily where we have rented an ocean villa for a month. Both of those trips I’ve pretty much paid for in advance. My tax preparer asked why I pulled so much money out last year. I told her I understand the ramifications of IRMA and increased tax brackets. But that’s what I saved the money for. Even with over 3 years of spending, I still have quite a bit more than when I retired. So I just bought myself another home in North Myrtle Beach. I plan to use the home as my base in between travel. I mortgaged it to the hilt as I know I won’t be even trying to pay it off. My house in Virginia is paid off and I’m trying to determine if i want to turn it into a VRBO or sell outright. I’m leaning to VRBO so that I can stay there on visits up to see friends and doctors. I’m eyeing a new Low Speed Vehicle for beach trips as I’m only a mile from the ocean. I probably need to upgrade my SUV. Then I get down to Myrtle and instead of buying all new furniture, I find myself finding bargains on Marketplace and having friends help me retrieve the items. Investing like treasure hunting is in my DNA and it can be very hard to pay full price!
I’m sort of in the same boat but on the West Coast… Enjoy the treasure hunts. Have a wonderful time on the cruise.
Sounds like a wonderful life! Same boat, different coast
I just had to click on this article, as I’m living it. I’ve been on my own pretty much since age 16 and I’m 66 now. After a very early career in IT, I worked as a DOD contractor for a employee owned company for 35 years. I had a serious conversation with myself about 10 years ago after my divorce. I decided what I really wanted from life, was to not have to work. I was already living well below my means and investing the rest. Every raise went to the 401k and the Roth catchup until it was maxed for the year. I lived on the same paycheck amount for 10 years. I own 3 vehicles all with over 190k miles, the newest being ia 2013 Honda Pilot. Any extras I wanted I paid for from my side business selling antiques, collectibles and junk, so I’m addicted to picking / treasure hunting. My job was extremely stressful as mistakes could cost warfighter lives. The treasure hunting became diversion therapy for the stress. But eventually my stress induced high blood pressure pushed me to retire In August of 2023. The market dropped significantly right after and I had left a highly compensated (for the East Coast) position. I was able to work from home with great benefits. But I got to where even dialing in to a daily 9AM meeting was just too much. Since retiring, I have taken 4 specialty music cruises and been on several trips around the US. I’m planning another cruise in January and an Italy trip of 2 weeks alone. Then I will meet friends in Sicily where we have rented an ocean villa for a month. Both of those trips I’ve pretty much paid for in advance. My tax preparer asked why I pulled so much money out last year. I told her I understand the ramifications of IRMA and increased tax brackets. But that’s what I saved the money for. Even with over 3 years of spending, I still have quite a bit more than when I retired. So I just bought myself another home in North Myrtle Beach. I plan to use the home as my base in between travel. I mortgaged it to the hilt as I know I won’t be even trying to pay it off. My house in Virginia is paid off and I’m trying to determine if i want to turn it into a VRBO or sell outright. I’m leaning to VRBO so that I can stay there on visits up to see friends and doctors. I’m eyeing a new Low Speed Vehicle for beach trips as I’m only a mile from the ocean. I probably need to upgrade my SUV. Then I get down to Myrtle and instead of buying all new furniture, I find myself finding bargains on Marketplace and having friends help me retrieve the items. Investing like treasure hunting is in my DNA and it can be very hard to pay full price!
Great article! It has really made me think. Both my parents did not do much in their later years – not even travel. My Mom liked to be at home, and she had a beautiful home. She did not have a lot of income, but she really enjoyed her life with friends and doing the things she loved like creating art after my parents divorced in their mid-50’s. My Mom lived to be 93, and lived in her own home until her death. My Dad is now 97. He is frugal and reluctant to spend on himself, even though it would make his life so much easier in a lot of ways.
I am now in my mid-50’s, still working. I could retire (financially), but I am hanging on for 2-5 more years for various reasons. I do like my job for the most part. However, I am now noticing that the older I get, I like to stay home rather than travel!
I like doing gardening, going for walks, reading, running, visiting friends/family and learning about personal finance/retirement/investing. All of those things are mostly free/inexpensive! So, maybe I already have saved “too much”. And, now, thanks to this article, I realize that maybe I am going to end up just like my parents!
Cheering for you!!!
Great article once again and you have captured the go-go, slow-go and no-go phases of retirement perfectly. The point is enjoy the heck out of the go-go phases and if you work for the man till your 65-67 you’ve already worked past them!
What I would say is that while your consumption declines as you age, your giving can increase. You can offset the decline in consumption with a systematic increase in giving. It can be to family, friends or your favorite charities. Medical research is my favorite because I get to see the impact of the money. I also donate heavily to Tunnels to Towers which builds homes for disabled veterans and first responders killed in the line of duty.
We work so hard to save and invest systematically and many people are very wired to not spend but it doesn’t have to be that way. You can put giving and spending on autopilot by using ratios. Give and spend systematically!
Brian, no disrespect,
but the way you worded: “builds homes for disabled veterans and first responders killed in the line of duty”.
A dead person cant live in a home. Im assuming that cause/charity builds home for the surviving families of the deceased and thats what you meant to say.
Sorry for the nitpick.
I’m 55. Retiring at year end. I work in financial services and see many of my peers and colleagues who have done very well, probably better than me, sticking around for “one more year”. It makes me feel like an outlier or that I am missing something. My decision was based on the exact points you made in the article – health and time become more valuable with each year that ticks by. The math says I’m good to go, the mental aspect is more challenging than I anticipated.
omg – this quote:
We spend so much time talking about how compounding works on the asset side. Nobody warns you that it also works on the behavior side. Forty years of telling yourself “no” builds a muscle that gets very hard to relax.
Wow. Great article. So many well worded, thought provoking concepts and truth here. This is one to be read over and over again. Thank you for sharing this one!
Thanks for reading and sharing Tiffany!
This is one of your better articles. I may feel that way because we are thinking long and hard about retirement. We are both 62 and have run our business for the last 25 years. I have put it on the market recently and have found there are a large number of buyers that do not have sufficient cash to put toward equity at the close. I have a financial background and find it hard to comprehend. I brought 45% to the closing table when I purchased the company. Once we sell, our liquid investments should exceed $8mil.
Even with that nest egg, I am not confident in having sufficient annual growth to cover my desired living expenses. College football and basketball are my drug of choice. Additionally, I am a huge tennis fan and want to attend 3 of the 4 majors annually, which is no small outlay.
After saving for 40 working years, I am finding it terribly difficult to be “ok” with large spending outflows. One would think that the next egg should produce 700k annually and I don’t spend over 400k today. Still, it is hard for me to get past the feeling like I need another 2mil in liquid investments to truly be on the safe side of the hill.
I find it amazing that I feel this way. I never (until the last 7 years) believed I would have anywhere near 10mil in investments…and yet, here I am.
You shouldn’t retire if you absolutely don’t want to. The main impetus for many people to do so at your income and wealth is due to a death of a friend or a family, or a healthcare of their own. Then the focus focuses on spending the best time when the healthiest on whatever they want.
And I’ll tell you that getting to $10 million will not change your life. And if you keep grinding to $15 million, or $25 million, your life won’t change either.
The health can fall off a cliff at any moment. So I would be more intentional with your spending if you can.
I retired in June 2025. The largest discretionary expense we made was when we bought another house in another state on a whim. A friend from college had just moved there and invited us to check it out. So we did. Bought a house and moved there within 3 months. The house was listed at $435K and we put 50% down, so about $220K. Didn’t hesitate for a single minute. We kept our original house which has been paid for since 2019 and our adult kids are caretaking the house for us. Also, we’re traveling to Korea to visit our son. He’s teaching English there for a year or two. That trip will cost about $15K. Not really an issue financially. We were aggressive savers while building companies.
Cool. What is your age to help us understand spending by age? Thx
I was 59 when I retired and my wife was 57. We had sold an IT services business after 20 years. We still have small residential rental management company. I realized that I had been working and supporting myself 100% since I was 19 (40 years of work!), so it was time to stop. When we retired, our net worth was about $5.5M… no sense in continuing the grind. Not sure if that counts as “retiring early”… lol
I spend way more than my parents ever did for all the reasons you’ve laid out. Some of this is generational mindset — my wife and kids love adventurous travel and once-in-a-lifetime experiences (e.g. exploring Singapore and staying at the Marina Bay Sands), while my parents would say “too far away and too fancy.”
I like the go-go, slow-go, no-go framework but I am very mindful that anything past age 65 is in the “You-Just-Don’t-Know Years”. I’ve seen people thrive and jet-set from 65-80, and I’ve seen people experience rapid decline. It’s a crapshoot! So for me, the goal is to plan financially for indefinite go-go years. It’s about always having the option. If life happens and we can’t go-go anymore, we’ll cross that bridge when we come to it but I’m not going to plan for no-go.
It really is a crap shoot after a certain age. My greatest shocks have been how quickly life can disappear once you get an illness.
Yuen specifically thinking about my father’s friend who was golfing one day and gone within six months after a diagnosis.
your revised chart with GO-GO until 55 fits pretty well with me. Retired at 53. Bought an adventure van at the start of COVID. We still have it and use it a lot. My wife and I have travelled globally extensively for pleasure and for work prior to retirement. We still do, although she’s still genuinely excited to do so more than I am these days. 59 now. She’s 63. In my case I still “get up and go” a lot. Mostly because I can and I fortunately have a circle of friends that are active and adventurous, so I go along to enjoy the camaraderie and activity. That said, in between those types of frequent trips, I thoroughly enjoy peace and quiet more than ever. As for spending, I still deliberate extensively even though there’s no actual financial reason to. I guess it’s habit more than anything…..and to minimize taxes! But if I do want something I do get it. Like a new (to me) Ferrari I don’t need. It’s a terrible financial decision and I consistently debate keeping it or selling it. It’s a ton of fun to drive on the one hand, but a costly one on the other. Affording it is zero issue financially. It just seems a bit much and really doesn’t get driven often since we travel so frequently. Anyway, just to say that I am allowing myself to spend a bit after working, saving, and investing since I was a kid, and having some fun while I can. :-). I definitely see myself slowing down over the next decade or so, just as your chart implies. In the mean time I’m trying my best to keep “doing things while I can” and enjoying family and friends as much and possible while I’m still young(ish)!
Great job going on an adventure after age 55! The time went quick, hasn’t it?
Can you give an idea of your net worth? Thx
Yes, time flies. Faster and faster the older we get it seems. A good reminder to “do it now, while we can”. This summer we spent 3.5 weeks camping our way across the country in our 4×4 van from one gorgeous hiking location to another. We’re heading back out in November for another 3 weeks to camp and hike in TN, TX, and NM. It’s good simple fun. As for nw we’re in the 10-15m range. Zero debt. Our targeted annual spending budget is $10k gross each ($20k total) in effort to stay in the 24% tax bracket. A year ago we bought our “forever home” with cash. It’s turn key which allows us to lock the door and leave. Love your posts and your books! Thanks for doing what you do! :-)
Certainly spending money is not in my DNA. I am 75 wife is 72. Both retired 3 yrs ago. We are spending money but not enough to the point that I am still able to invest about $60-70K a month. That money comes from reinvested dividends and stock trading that both of us are good at. The only big ticket item we purchased in the last couple of years was a larger house we bought for cash last year and moved in recently. Putting new roof on it was another $100K. Property taxes on our properties amount to $42K/year and maintenance adds another 15K. So we live a very high high fixed cost life but beyond that we are tight on money. New couches and patio furniture will have to wait until next year. So does another cruise. Car upgrades are budgeted for 2028 and beyond. Until our old home sells hopefully this year we sit tight and count our blessings.
Wow! Being able to spend $60-$70K a MONTH at your age is enormous!
If you have kids, are they all set up with houses, retirement, etc? How about grandkids?
Is there anything you would have done differently if you rewound time 20-30 years ago?
I am always trying to look ahead to see where the blind spots are. And I really don’t want to have the capacity to reinvest that much so I’m thinking once I turn 50 next year, to just really dial it down and take it easy. The traditional retiree lifestyle. But then I realized I have a new book coming on next fall that I need to market.
Other than very high fixed cost of our residences we spend very little on ourselves. Our daughter is planning FIRE in a couple of years so most of the money will be left to our grandchildren. Anything we would have done differently 20-30 yrs ago? I don’t think so. We have always pushed everything to the max and made good financial decisions. I don’t think we could have done better given the fact that until 5 yrs before retirement our combined gross income did not exceed $200K.
Good stuff. Can you share your estimated net worth? It is helpful for context. What did y’all do for a living?
College professor with $85K highest salary. Net worth around $15M.
Awesome! Were there any particular Investments that did well for you?
How come more people earning $85,000 a year are not worth $15,000,000, 50 years later?
It seems so obvious if you just run the numbers that eventually your wealth come down to significant levels after a long enough time. But people aren’t saving and investing as much as they should.
I think it depends on the individuals. After cancer two years ago my husband and I decided to travel aggressively until we couldn’t anymore. At 69 & 88 we are currently spending 10 weeks in Barcelona, Rome & Paris. Walking an average of 5.7 miles each day and navigating 58 worn marble steps to our 4th floor flat multiple times each day. We joke with our kids that we are spending their inheritance and they are all for it.
Oh, and we just finished our “age in place” new house with everything in it that our little hearts desired.
Walking over 5 miles a day at your age is wonderful here. Very inspiring!
Was it the cancer that jolted you two to start spending, traveling, and living it up more? If so, do you think that if he did not get cancer, your life would’ve been much more frugal and less adventurous as a result?
What do you think you should’ve done differently in your 40s and 50s? Thanks for all the wisdom.
My out-of-the blue cancer at 67 just reminded us that tomorrow isn’t promised and we threw out the travel budget and go whenever we feel like it. We booked a cruise to Alaska that left in 2 weeks when our son & family said they could go that week. We keep inviting family to join us as that is our greatest joy and we know the grandkids will soon have their own interests.
I was fortunate to retire at 42 after selling a business and because of our 19 year age difference we have always been aware that we may not have the time other couples have. Happy to be celebrating 45 years this year and my 88 year old husband, with his good Norwegian genes, can out-walk me. We are less careful with money now than in the past because our portfolio has done well and we have always spent less than our income. It might make sense for us to start giving more to our heirs now beyond the 529’s etc.
Thanks for your writing. I have referred your newsletter and given your books to many and hope they get as much from them as I do.
Wonderful! And thank goodness you are cancer-free! May you and your husband have the best of health and adventures.
Thank you for reading and sharing my newsletter and work over the years.
To many more incredible adventures!
Hi Sam,
Good piece and a strong argument for Bill Perkins’s Die with Zero framework.
In the past, you’ve mentioned that he’s a multi-millionaire nat gas trader and HF principal so his financial philosophy doesn’t broadly apply. Here, you’re more aligned.
Would like to hear your current views and if they’ve changed and/or softened.
Keep up the good work and hope you treat yourself for the big 5-0
I’ve actually been writing about decumulation well before that book came out, and he has commented and reached out to me before. After all, I started writing about FIRE in 2009 and left in 2012.
It’s a good message, but I just want people to be careful that Bill had over $100 million in net worth when that book came out and it has surely since grown. It is a luxury belief to tell people to die with zero when you have so much money.
My parents are 70 and 81 and spending more money than ever. They and their RV friends rent expensive rental pads in resorts in Florida a few months of the year ($$$) where they all play pickleball 5 days a week. They now happily outsource lawn care, cleaning, and some cooking. On top of the 100k RV that rapidly depreciates and costs a fortune to maintain.
They love spending money on cars! It helps that their money comes from pensions and social security. They would be a lot more cautious if it came from a pot of money.
At 64 (when my father was 79) my parents moved country (partly to be near my brother and their grandchildren). But after my father died at 86 years old my mother really didn’t spend much though she had almost $3 million. The biggest thing she did was buy some stamps, which were being auctioned for charity. Now I am 61 and retired but I have children aged 7 and 10. So, I’m definitely going to be spending lots of money for the next 10 years!
I think you shouldn’t just be in saving mode up to 45. Live life more consistently across the years. I was going into debt up to age 30…
Can you share your thought process of having children at ages 51 and 54? How old is your wife? Thx
Read “Die With Zero.” I too worked too long (retired at 60) and saved too much. I now plan to donate $111,000 tax free to charities every year from my IRA and it will still probably last 30 years! I recently ditched my 40-year-old Acura Integra. There’s still several million in other accounts which at even a modest 6% average growth rate will be challenging to spend down. Like you said, it’s in my DNA not to waste money. I don’t want to fly first class on my yearly trips to Japan; economy is just fine, and you still have to wait in the same lines with everyone else at immigration and customs and baggage claim anyway. My wife likes the challenge of using coupons to get the best deals on groceries, even though the money she saves is in the noise level. We’re trying not to sweat the small stuff anymore, but it’s challenging to find worthwhile causes where you think a sizeable donation would have a significant impact. We’re not in the $100 million class which gets buildings and schools named after you (we recently happened to meet Bob and Connie Lurie at a charity event!).
Yep, Bill has been reading my work. But be careful. Bill was worth over $100 million when he published it, so it’s easier to die with zero when you’ve got lots of money.
It’s a luxury belief folks with lots of money have that they like to convey to others. It makes wealthy people feel better.
Read “Die With Zero.” I too worked too long (retired at 60) and saved too much. I now plan to donate $111,000 tax free to charities every year from my IRA and it will still probably last 30 years! I recently ditched my 40-year-old Acura Integra. There’s still several million in other accounts which at even a modest 6% average growth rate will be challenging to spend down. Like you said, it’s in my DNA not to waste money. I don’t want to fly first class on my yearly trips to Japan; economy is just fine, and you still have to wait in the same lines with everyone else at immigration and customs and baggage claim anyway. My wife likes the challenge of using coupons to get the best deals on groceries, even though the money she saves is in the noise level. We’re trying not to sweat the small stuff anymore, but it’s challenging to find worthwhile causes where you think a sizeable donation would have a significant impact. We’re not in the $100 million class which gets buildings and schools named after you (we recently happened to meet Bob and Connie Lurie at a charity event!).
“they said they can’t be bothered. They also don’t want to risk getting sick.
So I offered to pay. A nice cruise, balcony suite, any duration, any location. My treat. They declined.”
Of course they did. They didn’t say they could not afford the cruise. They said they didn’t want to go.
You should be a good boy and listen to your parents. :-)
Seriously though, that spending curve is most likely explained not by people become more frugal as they age, but by the fact that most of the extra money spent in the 25-50 range is sent on raising kids not on themselves.
Yep, they don’t want to go and they don’t want to get sick.
How have you noticed your parents spending money?
You seem to be over 50, how are you spending money and are you still working?
I’m 78 and my wife is 75. I think the 70’s is young enough to do pretty much anything you want. I retired at 65. I spend more money now than ever. When someone is retired they have more time to spend I still can bike, kayak, play golf, snorkle, walk. Tennis is out with knees and lower back not so great. The last 2 years took 30 day cruise around Asia and 55 day cruise around South America and Antartica. So I say spend your money if you have it. Use passive income for basic spending and spendm the rest for fun. Next summer taking driving up into northern Canada and Canadian Rockies. Right now I’m at the beach for a week in Oceanside Ca. We went kayaking in harbor today with our inflatable kayaks which we take everywhere.
Very awesome to hear Steve.
I just finished playing tennis and my knees are sore and my back is in pain. And now I need to go take a shower and nap. So I don’t have Faith my back will hold up in 20 years. But it’s nice to know you are doing a lot of other cool stuff.
To your great health!
Go-Go years (Up to 45). Sam that is not any traditional understanding. I am 62 and golf 5 days a week, work out, travel 4 major trips a year. Walk European 80-mile trails.
Go-Go years – 55-70
SLow-go – 70-85
No-go – 85+
You can’t look at “peak spending”. 40s is when you are spending on mortgage, schools, colleges..alot of that spending is on others.
I am doing all kinds of things under Go-Go but not spending much more because it is now mostly all just on us (wife and I)
At 49 with your level of apparent health, you have at least 20-25 go-go years left.
55 is a more appropriate start. And I think a lot of men starting at 50 have existential crisises and start spending more too. I know I plan to.
I’ve updated my chart! Well done on staying so active at your age.
Just one thing though, i’ve seen so many people stay active in their 60s, and then suddenly, there is a cliff due to some type of illness or disease. It’s actually kind of scary to see.
My dad used to golf with his friend named Terry, and then one day Terry got cancer, and he was gone six months later.